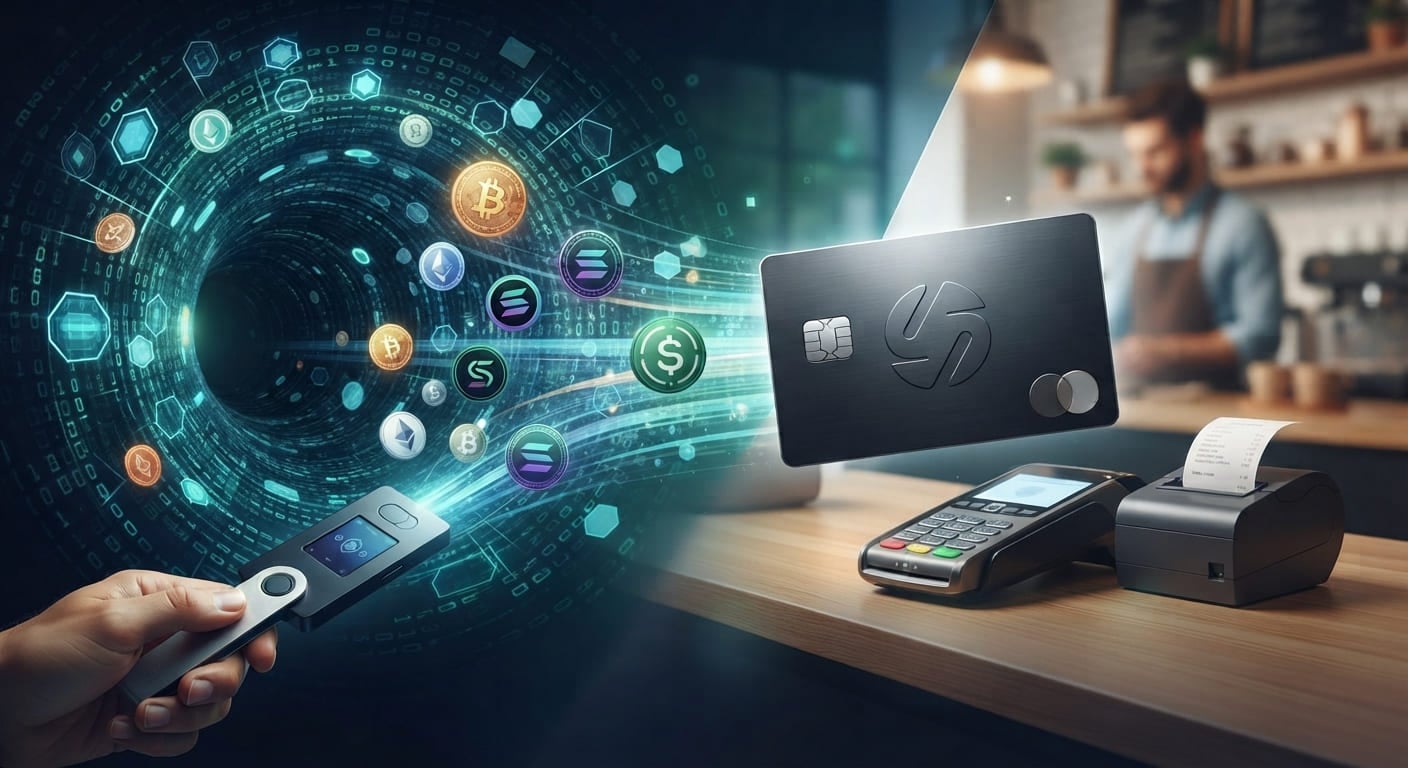
Crypto cards promise a simple thing: spend your digital assets like regular money, anywhere a card network is accepted. In practice, the category covers very different products. Some cards keep your funds in your own wallet until the moment you pay. Others require you to hand custody to an exchange or card issuer first. Some pay cashback in a stable, dollar-pegged token; others pay in a volatile native token tied to staking requirements. Before choosing one, it helps to understand what you're actually agreeing to.
What a crypto card actually does
At checkout, a crypto card converts a balance of digital assets into fiat currency in real time, or draws from a fiat balance you funded earlier by selling crypto. The merchant is paid in euros, dollars, or the local currency; your crypto balance goes down by an equivalent amount. The card itself runs on a standard network like Visa or Mastercard, so acceptance is rarely the limiting factor — the differences that matter are in custody, fees, and rewards.
Debit, credit, and prepaid: the three main structures
A debit-style card spends from a balance you already hold, converting crypto to fiat either in advance or at the moment of purchase. It's the most common structure and the easiest to reason about day to day.
A credit-style card lets you spend against a credit line, sometimes backed by crypto held as collateral, and settles in fiat. If you don't pay the balance in full, interest applies — the tradeoff is that you avoid selling your crypto to spend.
A prepaid card only lets you spend what you've loaded onto it in advance. There's no credit check and no credit line, which makes budgeting simple but limits flexibility.
Self-custody versus custodial cards
Most crypto cards on the market are custodial: the issuer or exchange holds your private keys and controls the underlying funds. This is usually simpler to set up, but it introduces counterparty risk — if the issuer runs into trouble, access to your funds can be affected.
What changes with a self-custody model
A self-custody card authorizes payments directly from a wallet you control, without moving funds to a third party first. You keep your private keys throughout. This doesn't eliminate every risk (wallet security is still on you), but it removes the specific risk of an issuer freezing or losing funds it was holding on your behalf.
What to check before choosing a card
Fees and hidden spreads
A card advertised as "no fees" can still cost you through the conversion spread — the gap between the market price and the rate you're actually given when crypto is converted to fiat. Foreign exchange fees are usually the largest hidden cost for anyone spending abroad, and they vary widely between providers.
How cashback is actually paid
Cashback paid in a stablecoin holds its value more predictably than cashback paid in a platform's native token, which can rise or fall with the market. A headline cashback percentage means less if the reward itself is volatile.
Staking and subscription requirements
Some of the highest advertised cashback tiers only unlock if you stake a meaningful amount of a native token for a set period, or pay a monthly subscription. It's worth calculating your real net reward once fees, subscriptions, and any opportunity cost of locked tokens are subtracted.
Regional availability
Not every card is available in every country, and rewards programs sometimes differ by region even when the card itself is offered. Always confirm availability and the exact terms for your country before applying.
Tax treatment: spending crypto is usually a taxable event
In most jurisdictions, using crypto to pay for something counts as a disposal, similar to selling it. That can trigger a capital gain or loss based on the difference between what you paid for the asset and its value at the time you spent it. Rules differ by country and can change, so this isn't a substitute for advice from a qualified tax professional who knows your situation. Spending from a stablecoin balance tends to simplify this, since the gain or loss on a currency-pegged asset is typically minimal.
Security and regulatory compliance
Card-level protections worth checking for include instant lock/unlock from an app, virtual card numbers for online purchases, and two-factor or biometric confirmation on payments. Beyond the card itself, check whether the issuer operates under recognized licensing — in the EU this increasingly means compliance with MiCA, alongside standard KYC/AML procedures. Licensing doesn't remove market risk, but it does provide a clearer framework for consumer protection.
Alternatives to a crypto card on Palzea
A card isn't the only way to put crypto to use day to day. If your goal is simply to hold value in a way you can convert easily, keeping part of your balance in a stablecoin such as USDC or USDT avoids most of the volatility that complicates card rewards and tax calculations.
If you'd rather put idle holdings to work, Palzea's Earn and Staking options let you generate yield on assets you're not actively spending — worth comparing against a card's cashback rate once fees are accounted for. If you need liquidity without selling your position, Borrow lets you use crypto as collateral for a loan, similar in spirit to a credit-backed card but inside your existing account. And if you occasionally need to move between crypto and local cash directly with another person, Palzea's P2P trading is another route worth knowing about.
You can check current trading conditions and available pairs any time on Markets, and see how account tiers affect trading costs on VIP and Fees.
A quick checklist before you apply for any crypto card
Custody: Do you know whether the issuer holds your funds or you retain your own keys, and are you comfortable with that tradeoff?
Real net reward: Have you subtracted fees, subscription costs, and any staking lock-up from the advertised cashback rate?
Currency of rewards: Is cashback paid in a stable asset or a token that can move against you?
Region and terms: Is the card actually available where you live, under the terms currently advertised — not just in marketing copy?
Tax record-keeping: Do you have a way to track each transaction for potential capital gains reporting?
Frequently asked questions
Are crypto cards taxed the same way in every country? No. Most jurisdictions treat spending crypto as a disposal subject to capital gains rules, but the specifics — rates, exemptions, reporting thresholds — vary and change over time. Check current guidance for your country or speak with a tax professional.
Is a "no-fee" crypto card really free? Not necessarily. Conversion spreads, foreign exchange charges, and ATM withdrawal fees are common even on cards marketed as fee-free. Read the fee schedule, not just the headline.
Do I need a crypto card to use my crypto day to day? No. Converting to a stablecoin, using P2P trading, or simply swapping to fiat when you need to spend are all alternatives that avoid card-specific fees and lock-in requirements entirely.
Crypto cards can be a convenient bridge between digital assets and everyday spending, but "convenient" and "cheapest" aren't always the same card. Weigh custody, real fees, and how rewards are actually paid before applying — and remember that crypto values are volatile, so any balance you plan to spend can be worth less by the time you use it.
Explore your options on Palzea: check Markets, put idle assets to work with Earn, or read more on the Palzea Blog. If you have questions, Support is there to help.